

What Is Modular Home Financing and How Does It Work?
Modular home financing can make factory-built housing feel less mysterious, but it is not always as simple as a standard mortgage. The loan may need to cover land, site preparation, transportation, foundation work, and the home itself. Lenders often review the builder, construction contract, appraisal, borrower’s credit profile, and project timeline before approving funds.
Tom Hardiman, executive director of the Modular Building Institute, has described modular construction this way: “Modular construction is a process, not a product.” That distinction matters. A modular home is typically built in sections inside a controlled factory, then transported and assembled on a permanent foundation. Financing may therefore begin with a construction loan and later convert into a long-term mortgage. Some lenders offer a single-close option, while others use separate stages. The details vary.
Timing matters.
Borrowers should ask when payments begin, how lender draws are released, and who pays for unexpected site costs. Soil testing, utility connections, permits, and delivery access can change the budget quickly. A low factory price may not represent the finished project cost. That is an easy mistake to make.
This guide explains how modular home financing works from application to closing. It also examines down payments, interest rates, appraisals, loan types, and lender requirements. Readers should compare written loan estimates and verify current terms with qualified professionals. Financing rules differ by location and lender. Even experienced buyers can overlook one expensive detail.
What Defines a Modular Home? Codes, Labels, and Fannie Mae Rules
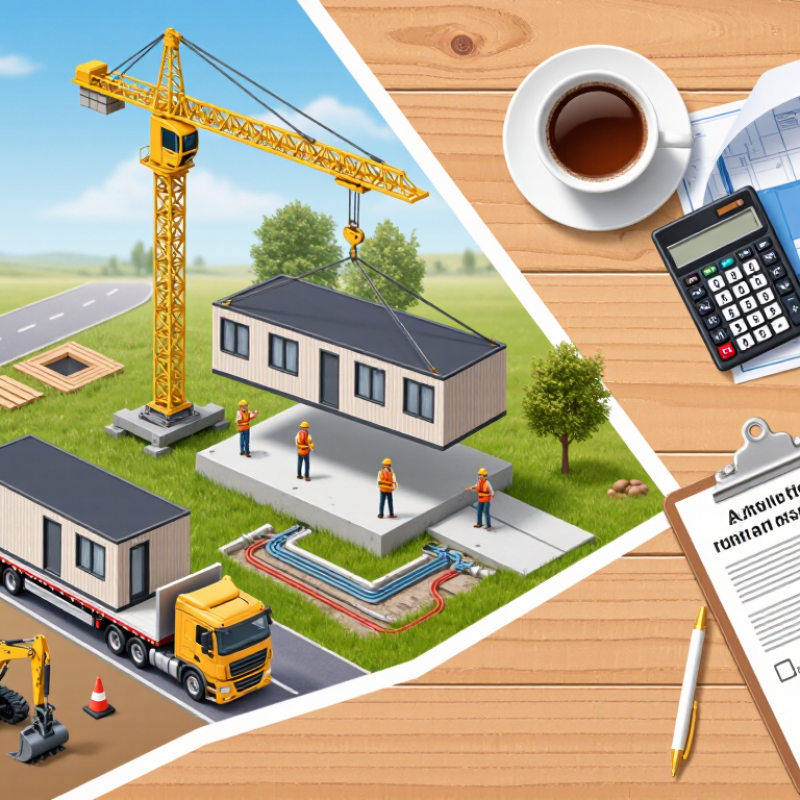
Modular homes are factory-built dwellings assembled in sections, then transported to a permanent site. Unlike manufactured homes, they follow state or local residential building codes. They usually do not carry the federal HUD label used for manufactured housing. That distinction matters. A 2024 Modular Building Institute report estimated the permanent modular construction market at about $20.3 billion, showing that factory construction is no longer a niche process.
Fannie Mae’s Selling Guide generally treats an eligible modular home like a site-built property. The home must rest on a permanent foundation, connect to normal utilities, and qualify as real property. Local inspection records should confirm code compliance. Appraisers also need comparable sales, accurate specifications, and evidence that the home is permanently attached. The label can still confuse borrowers.
A modular home may have a state certification plate, serial documentation, or manufacturer records. Those documents are not automatically interchangeable. Fannie Mae rules focus on construction standards, ownership, and appraisal treatment, rather than factory appearance alone. The U.S. Census Bureau’s 2023 Characteristics of New Housing report recorded a median new-home size of 2,411 square feet, but size does not determine financing eligibility. I would not rely on the word “modular” alone. Ask the lender to review the plans, foundation details, title status, and inspection trail before ordering an appraisal. Small paperwork gaps can create large delays.
What Is Modular Home Financing and How Does It Work? - What Defines a Modular Home? Codes, Labels, and Fannie Mae Rules
| Topic | What It Means | Typical Requirement or Data Point | Financing Relevance |
|---|---|---|---|
| Basic definition | A modular home is a dwelling constructed in sections or modules in a factory and then transported to the building site for final assembly. | The completed home is intended to function as a permanent residence and is normally installed on a permanent foundation. | It may qualify for real-estate mortgage financing when it meets applicable property, legal, appraisal, and underwriting requirements. |
| Construction method | Major building components are produced indoors under controlled factory conditions, then delivered and joined on site. | Factory construction can reduce weather exposure and may shorten on-site construction time, although site work can still take several weeks or longer. | Lenders generally evaluate both the home and the land, including transportation, installation, utilities, permits, and site preparation costs. |
| Applicable building code | Modular homes are generally built to the residential or building code adopted by the state or local jurisdiction where the home will be installed. | Requirements may cover structural design, electrical systems, plumbing, mechanical systems, energy efficiency, fire safety, and local zoning. | Evidence of code compliance and final approval may be required before a lender treats the property as a completed dwelling. |
| Modular versus manufactured | A modular home is generally distinguished from a manufactured home by the construction-code framework and certification system used during production. | Manufactured homes are built under a federal manufactured-housing construction and safety standard; modular homes are generally built under applicable state or local codes. | The distinction affects documentation, titling, appraisal treatment, eligible loan programs, and whether the home is classified as real property. |
| Labels and certifications | A modular home may have state or local inspection labels, insignia, plan approvals, or certificates showing compliance with the relevant code. | The exact label format varies by jurisdiction; a federal manufactured-home certification label is not the defining label for a typical modular home. | The lender, appraiser, title company, and local authority may review labels, permits, inspection records, and certificates of occupancy. |
| Permanent foundation | The modules are placed on a foundation designed for the property and connected to the site in accordance with approved plans. | The foundation type may include a basement, crawl space, slab, or another approved system, depending on site conditions and local requirements. | A permanent foundation supports classification as real property and is commonly important for long-term mortgage eligibility. |
| Real-property status | The home and land are treated as one real-estate asset rather than as a separately titled movable item. | The borrower typically owns the land or has a legally acceptable interest in it, and the home is legally attached to the land. | Real-property status is generally more compatible with a conventional mortgage than personal-property financing. |
| Fannie Mae eligibility concept | Eligible modular homes are generally evaluated as site-built homes when they satisfy applicable requirements and are permanently attached to the land. | The property must meet applicable laws, be suitable for residential use, and satisfy underwriting, appraisal, title, and property-condition standards. | The presence of factory construction alone does not automatically disqualify a home from conventional financing. |
| Appraisal requirements | An appraiser estimates market value using the home’s location, condition, quality, design, site, and comparable properties. | Comparable sales should be reasonably similar; the appraisal should address the modular nature of the property when it affects marketability or value. | The appraised value helps determine the maximum loan amount and whether the proposed cost is supported by the market. |
| Construction-to-permanent financing | This loan structure can combine construction financing with the permanent mortgage used after the home is completed. | Funds may be released in stages for land, foundation, transportation, installation, inspections, and approved construction expenses. | It can reduce the need for separate loans, but the lender must approve the plans, budget, builder, schedule, and final property. |
| Down payment and loan amount | The required down payment depends on the loan program, borrower qualifications, property type, occupancy, and lender rules. | The loan-to-value ratio is calculated from the lender’s accepted value and eligible costs, subject to program limits. | A larger down payment may be needed when the appraisal is below the total project cost or when the loan program has stricter requirements. |
| Borrower documentation | The borrower must document income, assets, debts, credit history, identity, and the intended use of the property. | Common records include income statements, bank or investment account statements, purchase documents, land records, and insurance information. | Complete financial documentation allows the lender to assess repayment capacity and verify the source of funds. |
| Project documentation | The lender may need detailed information about the home, land, construction contract, site work, and installation. | Typical items include plans, specifications, itemized cost estimates, permits, survey information, foundation plans, delivery details, and inspection records. | Missing or inconsistent documents can delay underwriting, increase conditions, or prevent the loan from closing. |
| Site and utility review | The site must support delivery, placement, access, foundation construction, and connection to required services. | Review areas may include zoning, road access, grading, drainage, water, sewer or septic, electricity, and other utility connections. | Unexpected site costs can increase the required cash contribution and change the project’s feasibility. |
| Closing and completion | The transaction closes after required underwriting, title, appraisal, insurance, permit, and legal conditions are satisfied. | For a home under construction, final completion may require inspections, a certificate of occupancy, lien releases, and confirmation that approved plans were followed. | The permanent mortgage generally becomes fully effective after the lender confirms completion and acceptable property condition. |
| Main financing risks | Potential risks include cost overruns, transportation delays, permit issues, unsuitable land, appraisal gaps, and incomplete site work. | A detailed budget should include foundation work, permits, delivery, crane or placement costs, utility connections, taxes, insurance, and contingency funds. | Early lender review and verified project estimates can reduce the risk of funding shortages or closing delays. |
Note: Financing eligibility, documentation, and underwriting standards vary by lender, property location, loan program, and current agency requirements.
Related Posts
-
2026 How to Finance Your Modular Home Effectively?
-

Top 10 Modular Home Financing Options You Should Consider
-
How to Create a 3D House Tour for Global Buyers?
-
Top 10 Essential Tips for Modular Home Financing Success
-
Why Choose Fabricated Homes for Your Global Sourcing Needs?
-
Top 10 Benefits of Choosing Modular Homes in Perth for Your Next Build